
NEW CLASS-ACTION SETTLEMENT
When Insurers Deduct Fees From a Total-Loss Settlement
Why the real question is where the money went
Fair Claims Stronger Consumers
Florida Class Action Settlement Returns Body Shop Total-Loss Fees Deducted From ACV Settlements
The settlement is a consumer win, but its larger significance may be the legal and economic question it exposes: what authority allows an insurer to shift a disputed claims expense into the policyholder’s property settlement, and who ultimately benefits when the insurer later monetizes the salvage?
A proposed Florida class-action settlement deserves attention well beyond the dollar amount involved.
In Maxim Kharevich v. Star Casualty Insurance Company, the plaintiff challenged, among other things, the insurer’s practice of deducting amounts it considered excessive storage and towing charges from insureds’ actual-cash-value payments on total-loss claims. Under the proposed settlement, qualifying consumers may recover certain storage and towing deductions previously applied against their ACV settlements.
Star Casualty denies wrongdoing, the court has not determined that the company violated the law, and the settlement remains subject to final approval.
The immediate significance is that money previously removed from consumers’ total-loss settlements may now be returned to those consumers. The more important contribution of the case may be the way attorney Andrew Irvin and the plaintiff’s lawyers framed the underlying problem. This was not fundamentally a dispute over whether a body shop charged too much for storage. It was about what happened to the insured’s money when the insurer disputed someone else’s invoice.
The repair facility is largely outside the contractual relationship at issue. It is not a party to the insurance contract, does not determine the insured’s policy benefits, does not receive the insured’s ACV payment, and generally does not participate in the insurer’s eventual salvage recovery. Its invoice may trigger the controversy, and its records may become important evidence, but the consequential financial transaction occurs between the insurer and its policyholder.
The Invoice Dispute and the Insurance Benefit Are Separate Transactions
Much of the collision industry has historically approached these disputes as questions about the reasonableness of the shop’s invoice. The insurer challenges a storage charge, the repairer defends its rate and authorization, and the discussion becomes a vendor-payment dispute.
Irvin’s framing separates that dispute from the insured’s contractual benefit. An insurer may have a legitimate disagreement with a repair facility over what it owes on an invoice. There may be lien statutes, storage laws, contractual arguments or other mechanisms available to resolve that disagreement. None of those issues, however, automatically establishes that the disputed amount may be removed from the money owed to the insurer’s own policyholder for the loss of the automobile.
That distinction changes the legal inquiry.
Rather than beginning with whether the shop’s storage charge was reasonable, the more important question is what policy provision, or legal authority permitted the insurer to resolve that dispute by reducing the insured’s property settlement. The plaintiff’s theory separated the shop invoice from the customer’s insurance benefit rather than treating the two obligations as interchangeable.
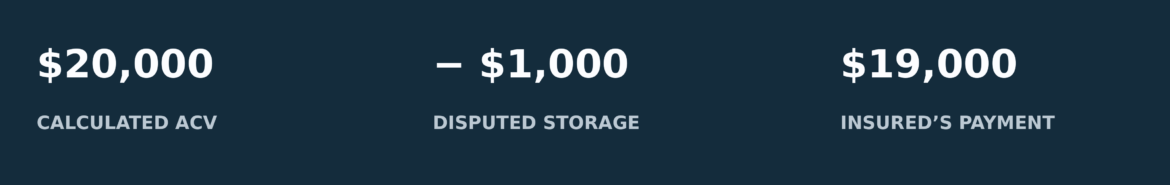
Consider a vehicle with a calculated ACV of $20,000. If the insurer disputes $1,000 in storage charges and deducts that amount from the property settlement, the insured receives $19,000. The repair facility may still have a billing dispute, but the policyholder has absorbed the immediate financial effect. The central issue is not simply whether the storage rate was excessive, but whether there was a contractual or statutory basis for shifting that expense into the insured’s settlement.
Why Small Deductions Can Produce Large Consequences
The amounts involved in an individual claim can make a case like this appear modest. The proposed settlement provides qualifying insureds with repayment of certain storage and towing deductions, subject to limits that include up to $25 per day for eight days, or $200, plus prejudgment interest for qualifying deductions.
Insurance claims operate at scale. A $200 reduction on one file is limited. The same methodology applied across hundreds or thousands of files produces a different financial effect. That is one reason class-action litigation often focuses on whether a common method or claims practice was repeatedly applied across a larger group of consumers.
The same concern becomes more significant as claims handling becomes more standardized and automated. A questionable judgment made manually may affect a single file. The same judgment embedded in a workflow can be repeated across thousands of claims. Standardization does not validate the underlying decision; it can simply magnify its consequences.
The settlement therefore carries significance beyond the repayment of relatively small deductions. It creates a concrete basis for examining every reduction from ACV as a separate decision that should have identifiable support in the policy, applicable law or another valid contractual obligation.
The Settlement Resolves One Issue, but Salvage Raises Another
My interest in this issue extends beyond the claims resolved by the Star Casualty settlement. Once the insured’s ACV payment is separated from the shop’s invoice, another financial transaction becomes visible: salvage.
A total-loss vehicle retains economic value even when repair is no longer economically justified. Unless the owner retains the salvage, the insurer generally takes possession of the damaged vehicle and monetizes the remaining asset through the salvage marketplace. Those proceeds become a recovery associated with the claim.
Using the same example, assume the insurer reduces the insured’s payment by $1,000 because of a disputed storage expense, leaving a $19,000 payment. The insurer then takes possession of the damaged vehicle and later sells the salvage for $6,000. The insurer has paid $19,000 and recovered $6,000 from the remaining property.
At that point, the analysis should extend beyond the reasonableness of the storage rate. The insured absorbed the disputed $1,000 expense. The insurer took possession of the asset, monetized it, and received the salvage recovery. That sequence raises a broader legal and economic question: whether an insurer that transfers an expense to its policyholder while retaining the economic benefit associated with the salvage has received a benefit at the insured’s expense.
The Unjust-Enrichment Question
The Florida settlement did not establish an unjust-enrichment claim, and the court has not ruled that this fact pattern constitutes unjust enrichment. I also have not identified a reported decision squarely addressing the precise sequence described here: a disputed storage or claims-related expense deducted from the insured’s ACV, followed by the insurer taking possession of the salvage, selling it, and retaining the resulting recovery.
That leaves an important area for legal analysis.
Unjust enrichment is not simply another label for an outcome that appears unfair. Its elements and availability vary by jurisdiction, and the existence of an express insurance contract can materially affect the analysis. Depending on the facts and applicable law, the more appropriate theory may involve breach of contract, an improper offset, restitution, unfair claims practices, unjust enrichment or another cause of action.
The economic transaction still deserves scrutiny. If the policyholder bears an expense associated with obtaining or disposing of the damaged asset while the insurer receives the full recovery from that asset, value has moved between the parties. The insured surrendered the vehicle and received less money because of the deduction. The insurer acquired an asset with residual value and used the proceeds from that asset to improve the net economics of the claim. Those facts do not establish unjust enrichment by themselves, but they provide a basis for examining whether the transfer was authorized and who ultimately benefited from it.
This is an area where total-loss litigation may be underdeveloped. Considerable attention has been paid to whether vehicles were properly valued. Less attention has been paid to what happens after the valuation is complete.
A Correct ACV Can Still Produce an Incorrect Settlement
Attorneys reviewing total-loss claims often begin with the valuation report, and appropriately so. Determining whether the valuation methodology produced a supportable ACV remains important. A valuation report and a settlement reconciliation, however, answer different questions.
The valuation report establishes what the automobile was worth. The settlement reconciliation explains what happened to the money after that value was established.
A vehicle can be correctly valued and the policyholder can still be underpaid if unsupported deductions are applied afterward. A complete analysis should therefore begin with the calculated ACV and then reconcile the deductible, taxes and fees, betterment or depreciation where legally permitted, towing, storage, administrative charges and every other offset that reduced the amount ultimately delivered to the insured. Each reduction should be traceable to a policy provision, statute or other legal authority.
The financial analysis may also need to continue beyond issuance of the settlement payment. Where relevant and legally obtainable, attorneys should examine possession, title, salvage disposition and recovery. If the insured’s payment was reduced because of an expense associated with the vehicle, understanding what happened when the insurer later monetized that vehicle may be necessary to reconstruct the full economics of the claim.
Collision repairers have a narrower role, but an important evidentiary one. Authorization records, storage dates, notices, insurer communications and vehicle-release documentation may help establish the sequence of events. The more useful inquiry is not simply whether the insurer paid the shop’s invoice, but what happened to the customer’s settlement because the insurer disputed that invoice.
Why I Wrote Total Loss Claim Handling
This case illustrates one of the central principles in Total Loss Claim Handling: File Process & SOPs: a total loss should not be treated as a single transaction.
ACV determination, the policy deductible, towing and storage, lien rights, title transfer, possession, salvage and the carrier’s recovery are separate legal and financial events occurring within the same claim. When those events are blended together, it becomes much harder to identify how money moved between the parties. Separating them changes the analysis.
That framework affects claim review, document preservation, discovery, appraisal analysis and expert work. It can also expose legal issues that remain hidden when every component of the claim is compressed into a single settlement event.
The handbook was written to help professionals examine the entire architecture of the total-loss file: what was owed, under what authority, when possession changed, where recoveries occurred, and how each transaction affected the insured.
A Consumer Win That Should Become a Foundation
The immediate result of the Florida settlement is significant. Consumers whose qualifying storage and towing deductions fall within the settlement terms may receive money back that had previously been deducted from their total-loss settlements. The identified class period runs from March 22, 2018 through June 26, 2026.
Its broader value may be the analytical foundation it provides. A disputed third-party expense should not simply appear as a reduction in an insured’s ACV payment without identifiable contractual or statutory authority. Once that issue is examined, the analysis should continue through the rest of the financial transaction, including possession of the damaged property and salvage recovery.
Future total-loss litigation may increasingly focus not only on whether the vehicle was undervalued, but on whether a correctly established value was later reduced through deductions that lacked proper support. That shifts the inquiry from valuation alone to settlement architecture.
For professionals who want to examine total-loss files at this transaction-by-transaction level, Total Loss Claim Handling: File Process & SOPs lays out the framework I use to separate valuation, settlement, possession, liens, storage, salvage and recovery rather than treating them as one financial event.
I also explore the Florida settlement and the broader unjust-enrichment question in the new members-only episode of Collision Coffee Talk.
The settlement may prove important not simply because money is being returned to consumers, but because it directs attention to a larger issue that deserves further legal development: whether every reduction from a total-loss settlement was authorized, and what happened to the economic benefit after the vehicle left the policyholder’s hands.